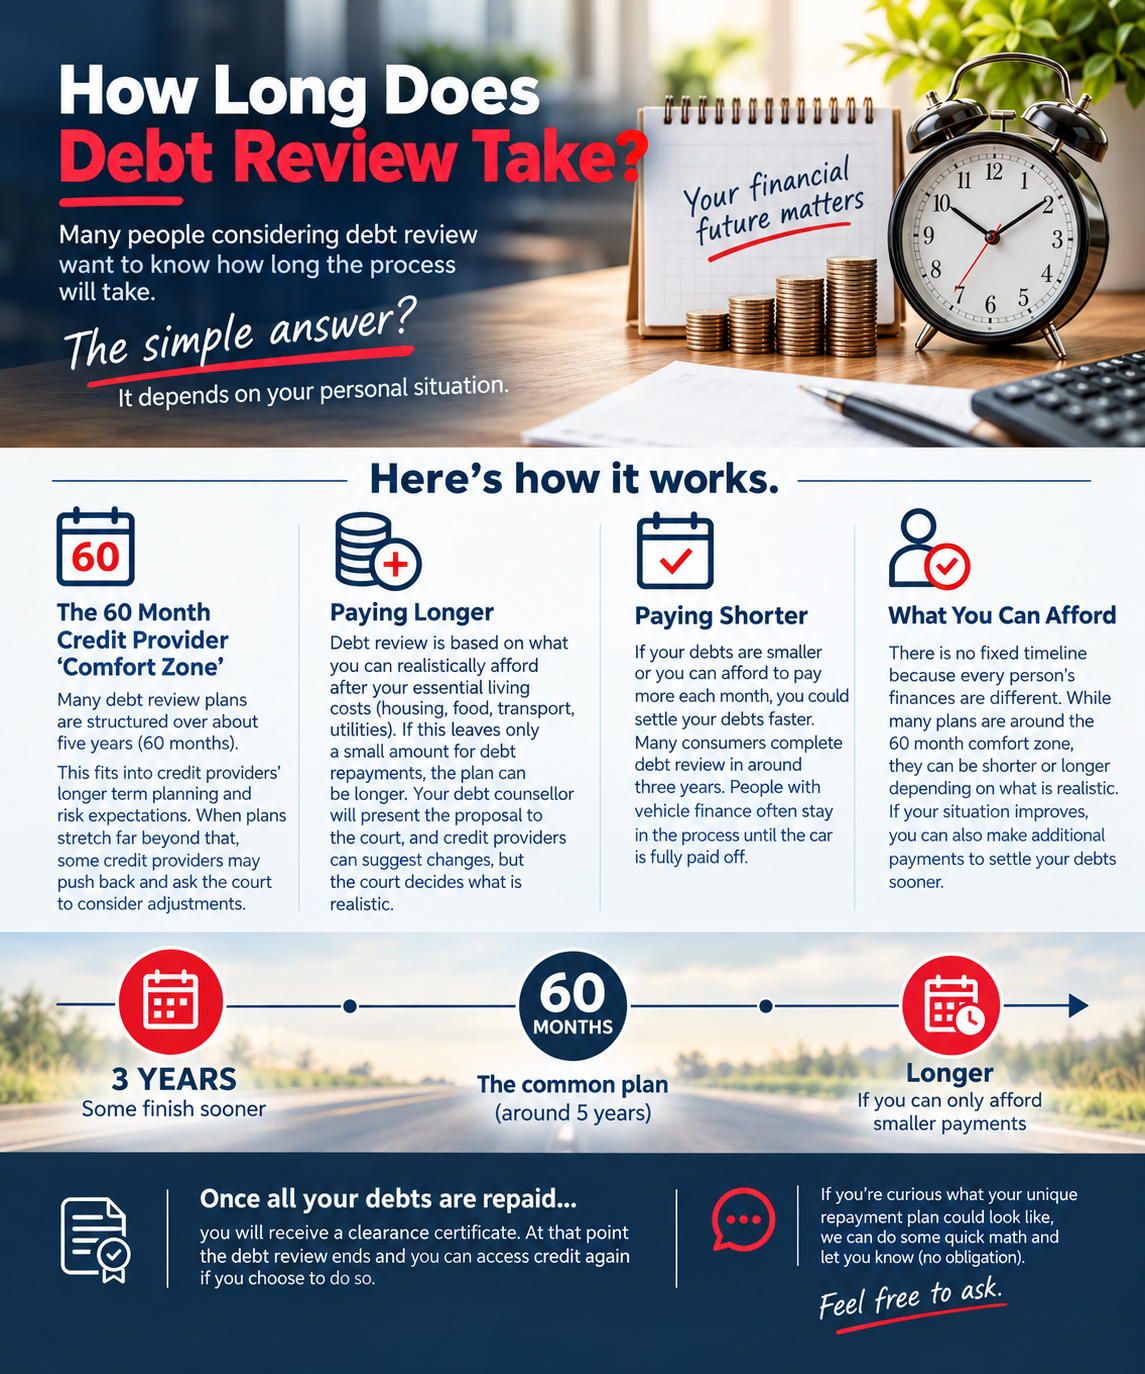
Many people considering debt review want to know how long the process will take.
The simple answer is that it depends on your personal situation. For many consumers, the plan runs for around 60 months, but some finish sooner while others take longer. The timeline is based on what you can realistically afford to repay each month.
Here is how that works.
The 60-Month Credit Provider ‘Comfort Zone’
Many debt review plans are structured over about five years.
This timeframe often suits credit providers because it fits into their longer-term planning and risk expectations. As a result, many repayment proposals are designed around 60 months. When plans stretch far beyond that timeframe, some credit providers may push back and ask the court to consider adjustments.
Paying Longer
Debt review is based on what you can realistically afford after paying for your essential living costs such as housing, food, transport and utilities.
Sometimes this leaves only a small amount available for debt repayments. When that happens, the repayment period can become longer. The debt counsellor will present the proposed plan to the court.
Credit providers may attend the court hearing and suggest changes if they feel the plan takes too long, but the court ultimately decides what is realistic.
Paying Shorter
In other cases, the timeline can be much shorter.
If your debts are smaller or you can afford to pay a decent amount each month, you may be able to settle your debts faster. Many consumers complete debt review in around three years. This gives them breathing room to stabilise their finances while still paying off their debts steadily.
People with vehicle finance often stay in the process until the car is fully paid off.
What You Can Afford
Debt review doesn't have a fixed timeline because everyone's finances are different.
While many plans are structured around the 60-month comfort zone, they can be shorter or longer depending on what is realistic. If your financial situation improves, you can also make additional payments to settle your debts sooner.
Once you repay all your debts, you will receive a clearance certificate. At that point, the debt review ends, and you can access credit again if you choose.
If you are curious what your unique repayment plan could look like, we can do some quick math and let you know (no obligation). Feel free to ask.